
Reverse Mortgage vs. Selling the Home to Fund Assisted Living or Long-Term Care
From our archive. This guide is being reviewed and updated under our editorial standards. Check figures against the official source before you act.
Sagewise is free to use and may be paid when you click links or submit forms on this page. That never changes what we write. How we make money
The decision to leave a long-time home rarely feels simple. Rising care needs, the cost of assisted living, or the prospect of full-time help can push the question forward. Two paths often stand out: sell the house and use the proceeds to pay entry fees and monthly charges, or keep the house and draw from a reverse mortgage to cover care while remaining in place.
Each choice carries different effects on cash flow, taxes, and what remains for heirs. This guide lays out the practical differences so you can weigh them against your own priorities of security, simplicity, and control.
Key Takeaways
- Selling converts the full equity into cash at once but ends ownership and may trigger capital-gains tax above exclusion limits.
- A reverse mortgage leaves you in the home, requires no monthly mortgage payment, and supplies tax-free loan advances for care costs.
- The stay-and-draw approach can delay or avoid facility entry fees while preserving the option to sell later.
- Both paths affect residual income calculations and Medicaid planning in different ways.
- Run the numbers on monthly care costs, remaining equity, and tax exposure before choosing.
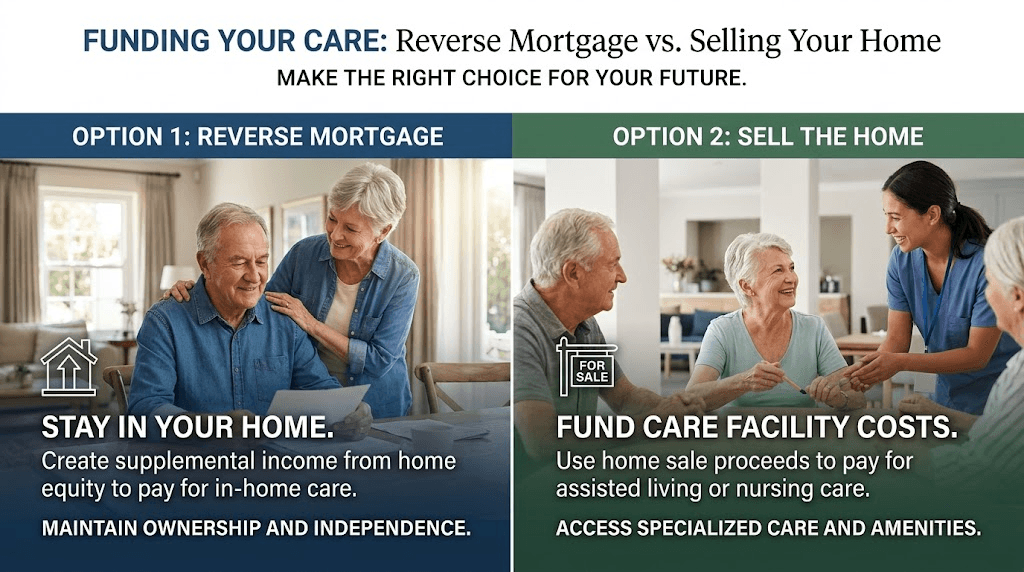
The Core Trade-Off: Cash Now Versus Control Over Time
Selling the home produces a single large sum after paying off any existing mortgage, closing costs, and possible capital-gains tax. That cash can cover an assisted-living entry fee and create a reserve for ongoing charges. Once the sale closes, however, the house and any future appreciation are gone.
A reverse mortgage, specifically an FHA-insured Home Equity Conversion Mortgage available to homeowners age 62 and older, converts a portion of the equity into loan advances. You continue to own the home and live in it. No monthly mortgage payment is required as long as you meet the basic obligations of property taxes, homeowners insurance, and maintenance. The loan balance grows over time and is repaid when the home is sold or no longer occupied as a primary residence.
The choice is not only financial. It is also about how long you want to remain in familiar surroundings and how much flexibility you want to keep for later decisions.
Cash-Flow Comparison
Assisted living and memory-care communities typically charge a substantial entry fee plus a monthly rate that covers housing, meals, and basic services. Those monthly rates often rise each year. Selling the home funds the entry fee and creates a pool of cash to cover the ongoing charges. When that pool runs low, other assets or family support may be needed.
A reverse mortgage can supply a line of credit, monthly tenure payments, or a combination. The funds can pay for in-home care, adult day services, or the monthly cost of an assisted-living community while you still own the house. Because the advances are loans rather than income, they do not increase taxable income or affect Social Security taxation in the same way as IRA withdrawals.
The stay-and-draw strategy works best when the equity is large enough to support needed care for a realistic period and when the home remains suitable for aging in place or for periodic visits if you later move to a facility.
Tax and Legacy Effects
Sale of a primary residence may qualify for the capital-gains exclusion of up to $250,000 for a single filer or $500,000 for a married couple filing jointly, provided ownership and use tests are met. Gains above those limits are taxable. Selling also ends any future step-up in basis for heirs on that property.
Reverse-mortgage proceeds are not taxable income. The loan balance, including accrued interest and mortgage-insurance premiums, is repaid from the sale of the home after the borrower permanently leaves. Heirs are never personally liable beyond the value of the home. If the home is worth more than the loan balance, the surplus belongs to the estate. If the balance exceeds the value, the FHA insurance covers the difference under the non-recourse feature.
Keeping the home under a reverse mortgage preserves the possibility of a later sale at a higher value and maintains the option for heirs to keep the property by paying off or refinancing the balance.
When the Stay-and-Draw Approach Often Makes Sense
- The home is paid off or has a modest remaining balance that a reverse mortgage can clear.
- In-home care or a lower level of facility care is sufficient for the foreseeable future.
- Remaining in a familiar neighborhood supports emotional well-being and existing support networks.
- Other assets are limited and selling would leave little reserve after entry fees.
- You want to delay an irreversible decision while testing care arrangements.
When Selling May Be the Clearer Path
- The home requires major repairs or is no longer safe or practical for daily living.
- Care needs are already at a level that requires full residential support and the equity will fully fund a stable long-term arrangement.
- Family members are unable or unwilling to manage the property from a distance.
- Property taxes, insurance, and maintenance costs remain high relative to available income even after a reverse mortgage.
Side-by-Side Decision Framework
| Factor | Selling the Home | Reverse Mortgage (Stay-and-Draw) |
|---|---|---|
| Immediate cash | Full net equity after costs and taxes | Portion of equity as loan advances |
| Monthly housing payment | None (new facility fees apply) | No required mortgage payment |
| Tax on funds received | Possible capital gains above exclusion | None (loan advances) |
| Control of home | Ends at closing | Continues while you live there |
| Legacy for heirs | Cash remainder after care costs | Remaining equity after loan payoff |
| Flexibility to change plans | Low once sold | Higher; can sell later if needed |
| Effect on Medicaid | Spend-down rules apply to cash | Loan proceeds must be spent carefully to avoid countable-asset issues |
Practical Steps Before Deciding
- Obtain a realistic estimate of current home value and remaining mortgage balance.
- Request written costs from one or two assisted-living communities, including entry fees and typical annual increases.
- Estimate the monthly cost of quality in-home care for comparison.
- Use the Home Equity “Cash Unlock” Calculator to see how much a reverse mortgage could provide based on age and equity.
- Speak with a tax adviser about capital-gains exposure on a sale and with a counselor about reverse-mortgage terms.
- Review how either path interacts with Medicaid eligibility and look-back rules if long-term nursing care is a future possibility.
Other Sagewise Services That Support the Decision
Sagewise is an independent comparison and matching service. It does not sell policies or originate loans. Once the numbers are clear, you can explore related options through the same free process:
- Reverse-mortgage and home-equity matching to compare current offers
- Cash-for-homes resources if a fast, simplified sale becomes the preferred route
- Home-warranty and aging-in-place tools that can reduce ongoing maintenance risk while you remain in the house
Each matching request carries no obligation. You receive information from pre-vetted providers so decisions stay in your hands.
Frequently Asked Questions
Can I take a reverse mortgage and still move to assisted living later?
Yes. The loan becomes due when the home is no longer your primary residence. You or your heirs then sell the property or repay the balance another way. Any remaining equity after payoff belongs to you or the estate.
Does a reverse mortgage affect eligibility for Medicaid?
Loan proceeds are not income, yet cash sitting in a bank account can count as an asset. Funds drawn must generally be spent on allowable expenses within the same month to avoid pushing countable resources over state limits. Planning the draw-and-spend sequence is essential.
What happens if the loan balance grows larger than the home value?
Under the FHA non-recourse rule, neither you nor your heirs owe more than the home is worth at the time of sale. The mortgage insurance fund covers any shortfall.
Is counseling required before a reverse mortgage?
Yes. HUD-approved counseling is mandatory. The session reviews costs, obligations, and alternatives so the decision is fully informed.
Closing Perspective
Neither path is automatically better. Selling provides a clean break and a defined pool of cash. Keeping the home with a reverse mortgage preserves control, eliminates the mortgage payment, and keeps future options open. The better choice is the one that matches your care needs, your comfort with ongoing home ownership, and your wishes for what remains for family.
Gather the actual numbers for your home and your care costs. Compare them side by side. Then decide with clear eyes rather than under pressure.
Compare reverse-mortgage and home-sale options with no obligation.
This guide is for general education and isn't individual financial, insurance, legal or tax advice. Spot an error? Tell us and we'll review it under our corrections policy.