
The 5 Best Whole Life Insurance Companies for Seniors (2025)
From our archive. This guide is being reviewed and updated under our editorial standards. Check figures against the official source before you act.
Sagewise is free to use and may be paid when you click links or submit forms on this page. That never changes what we write. How we make money
If you’re a senior, you’re not looking for a complex investment. You’re looking for a simple, permanent life insurance policy to provide a payout to your loved ones when you die.
A Whole Life policy is the perfect tool for this. It’s a permanent policy, which means it will never expire, and the monthly premium is locked in for life.
But this is where most people get confused.
An Honest Filter: "Whole Life" vs. "Final Expense"
When you see ads for “Whole Life,” you’ll often see two very different things.
- “Investment-Grade” Whole Life: This is what most financial sites (like NerdWallet) review. These are massive policies ($500,000+) with complex “cash value growth” features and premiums that can be **$700/month or more**. This is a high-end investment tool for a 45-year-old.
- “Final Expense” Whole Life: This is the right tool for most seniors. It is a type of whole life policy that is simple, small, and affordable. The goal isn’t “investing”; it’s covering your funeral costs with a $10,000 – $25,000 policy.
This review is for Option 2. We’ve reviewed the best companies that specialize in simple, affordable, “no-exam” final expense policies for seniors.
Key Takeaways
- Best Overall:Mutual of Omaha offers the best balance of trust, affordability, and easy (no-exam) approval for seniors in average health.
- Best for Brand Trust:AARP (by New York Life) is backed by two of the most trusted names for seniors and has rock-solid financial strength.
- Best for Health Issues: If you have serious health conditions, Colonial Penn and Gerber Life offer “Guaranteed Acceptance,” meaning you cannot be turned down.
The Best Senior Whole Life (Final Expense) Companies at a Glance
| Company | Sagewise Rating | Best For | No-Exam Type |
|---|---|---|---|
| Mutual of Omaha | 5.0 / 5.0 | Best Overall | Simplified |
| AARP (New York Life) | 4.5 / 5.0 | Brand Trust | Both |
| Colonial Penn | 4.5 / 5.0 | Guaranteed Acceptance | Guaranteed |
| Foresters Financial | 4.0 / 5.0 | Member Perks | Simplified |
| Gerber Life | 4.0 / 5.0 | Guaranteed Approval (50-80) | Guaranteed |
Best Overall: Mutual of Omaha
Bottom line: Mutual of Omaha is one of the most trusted names in senior insurance. Their “Living Promise” whole life plan is a near-perfect balance of fast approval, reliable coverage, and affordable, locked-in premiums.
- Financial Strength: A+ (Superior)
- No-Exam Options: Yes (Simplified Issue)
- NAIC Complaints: Far fewer than expected
- Policy Type: Permanent (Whole Life)
Sample Monthly Rate (Female, 65): $50 – $65 for $15,000
Sample Monthly Rate (Male, 65): $65 – $80 for $15,000
Company Overview: This is our top pick for most seniors who are in average health. The “Simplified Issue” application can be done over the phone in minutes. You just answer a few health questions, and approval is often instant. Their plan also includes an “Accelerated Death Benefit” for free, allowing you to access your benefit early if you’re diagnosed with a terminal illness. It’s the gold standard for final expense coverage.
Compare My Rates at Mutual of Omaha
Best for Brand Trust: AARP (by New York Life)
Bottom line: This policy combines two of the most trusted names for seniors: AARP and New York Life. You are getting a rock-solid policy from one of the world’s strongest and oldest insurers.
- Financial Strength: A++ (Superior – New York Life)
- No-Exam Options: Yes (Simplified & Guaranteed)
- NAIC Complaints: Far fewer than expected
- Policy Type: Permanent (Whole Life)
Sample Monthly Rate (Female, 65): $60 – $75 for $15,000
Sample Monthly Rate (Male, 65): $75 – $90 for $15,000
Company Overview: The AARP program offers two permanent policies for its members. The first is a Simplified Issue plan (up to $50,000) that just requires you to answer a few health questions. The second is a Guaranteed Acceptance plan (up to $25,000) that has no health questions at all. For seniors who value brand trust above all else, this is the most secure and reliable choice on the market.
Best for Guaranteed Acceptance: Colonial Penn
Bottom line: You’ve seen the TV ads. Colonial Penn’s plan is simple: if you are in the eligible age range, you cannot be turned down for any health reason. This is the ultimate “peace of mind” for those with serious health conditions.
- Financial Strength: A- (Excellent)
- No-Exam Options: Yes (Guaranteed Issue)
- NAIC Complaints: About average
- Policy Type: Permanent (Whole Life)
Sample Monthly Rate (Female, 65): $64 – $75 for $10,000
Sample Monthly Rate (Male, 65): $85 – $95 for $10,000
Company Overview: Colonial Penn is a straightforward solution for seniors who are worried they won’t be approved. The application has zero health questions. This policy does have a 2-year “graded benefit,” (as do most guaranteed plans), which means if you pass from natural causes in the first two years, your family gets a refund of all premiums plus interest. After two years, the full benefit is active. It’s the best way to get coverage if you’ve been turned down elsewhere.
Compare My Rates at Colonial Penn
Best for Member Perks & Riders: Foresters Financial
Bottom line: Foresters Financial is a “fraternal benefit society,” which means that in addition to your policy, you become a member with access to unique perks, including grants, scholarships for your family, and legal services.
- Financial Strength: A (Excellent)
- No-Exam Options: Yes (Simplified Issue)
- NAIC Complaints: Far fewer than expected
- Policy Type: Permanent (Whole Life)
Sample Monthly Rate (Female, 65): $55 – $70 for $15,000
Sample Monthly Rate (Male, 65): $70 – $85 for $15,000
Company Overview: Foresters’ “PlanRight” whole life policy is a strong, affordable option for seniors in average health. But its real value is in the “fraternal benefits.” As a member, you get access to legal-support services to help you write a will, a “Member Assistance” program for financial hardship, and scholarship opportunities for your children and grandchildren. It’s a policy that offers benefits to your whole family while you’re still living.
Compare My Rates at Foresters Financial
Best for Guaranteed Approval (Ages 50-80): Gerber Life
Bottom line: While famous for their “Grow-Up Plan,” Gerber Life is also a major provider of “Guaranteed Issue” whole life insurance for seniors. Their plan is simple, well-known, and offers coverage up to $25,000.
- Financial Strength: A (Excellent)
- No-Exam Options: Yes (Guaranteed Issue)
- NAIC Complaints: Fewer than expected
- Policy Type: Permanent (Whole Life)
Sample Monthly Rate (Female, 65): $65 – $80 for $10,000
Sample Monthly Rate (Male, 65): $88 – $100 for $10,000
Company Overview: Like Colonial Penn, the Gerber Life Guaranteed plan has no health questions and no medical exam. Approval is guaranteed for applicants between 50 and 80. It’s a reliable, brand-name choice for anyone with pre-existing health conditions. It also has a 2-year graded benefit. It’s an excellent, simple solution to ensure your final expenses are 100% covered.
Compare My Rates at Gerber Life
How We Rate the Best Whole Life Companies for Seniors
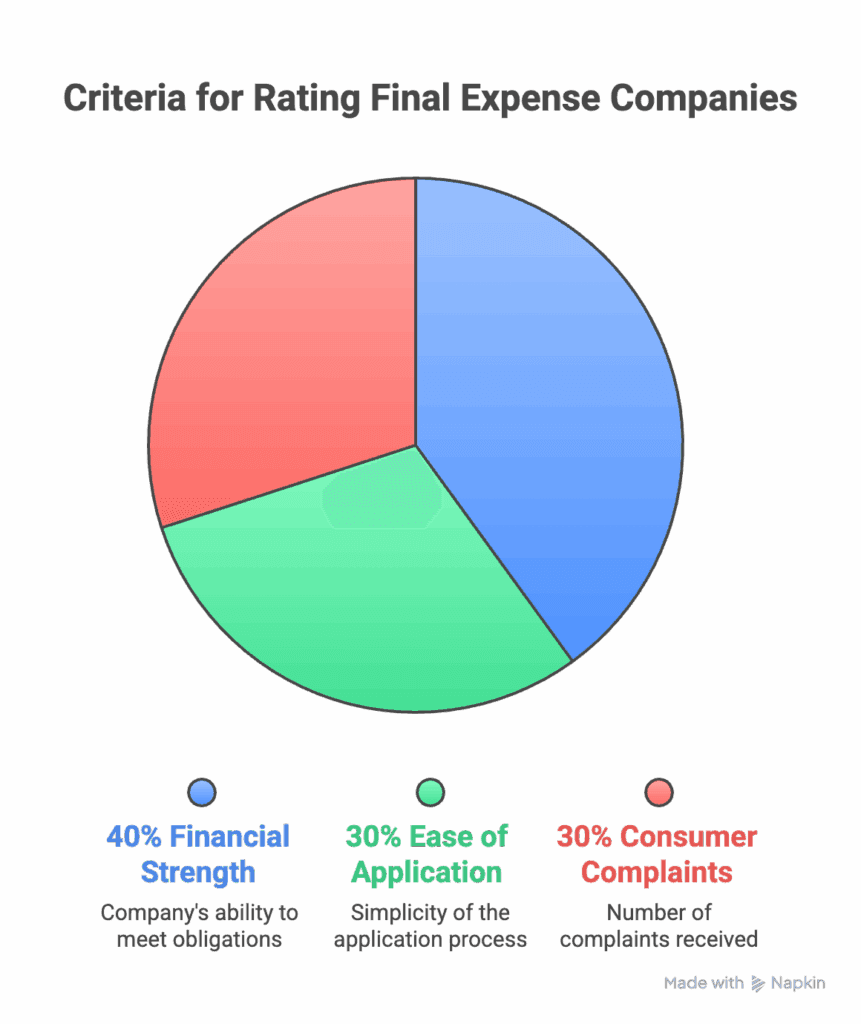
At Sagewise, our ratings are focused on what matters to a senior on a fixed income. We are not looking at factors for a $1M “investment” policy; we are looking at the factors that guarantee a smooth, reliable process for a final expense plan. We weigh these factors carefully:
- Financial Strength (40%): We useAM Best ratings. A life insurance policy is a long-term promise, and this “grade” proves a company is financially sound and will be there to pay the claim for your family, even decades from now. This is non-negotiable for us. We prioritize companies with an “A” rating (Excellent) or higher.
- Ease of Application (30%): We give higher scores to companies that make it simple for seniors to get coverage. We know our audience wants to avoid medical exams, so we prioritize companies with clear “no-exam” options. We look for both “Simplified” (for healthy seniors) and “Guaranteed” (for all seniors) plans. Companies that offer a fast approval process (often instant, over the phone) receive a higher rating because they remove anxiety and hassle.
- Consumer Complaints (30%): We check the National Association of Insurance Commissioners (NAIC) complaint index. This is the most important predictor of your family’s experience. This data shows if a company pays claims fairly and on time, or if they have a history of fighting with beneficiaries. A low complaint ratio is the strongest indicator of a smooth, hassle-free payout.
Your 4-Step Buyer's Checklist
Use this simple, non-interactive checklist to find the right policy for you.
- [ ] 1. Assess Your Health: This is the most important step. Are you in average health (you’ll want a ‘Simplified’ plan) or do you have significant health issues (you’ll need a ‘Guaranteed’ plan)?
- [ ] 2. Calculate Your Coverage: Find your ‘Peace of Mind’ number. Do you need $10,000, $15,000, or $25,000?
- [ ] 3. Check the Company’s Rating: Is the company you’re considering rated ‘A’ or higher by AM Best? Don’t settle for less.
- [ ] 4. Compare 2-3 Quotes: Never take the first price. Use an independent broker (like Sagewise) to get multiple quotes to ensure you’re not overpaying.
Alternatives to Whole Life
- Term Life Insurance: This is not a good choice for final expenses. It is temporary and will expire, leaving you with no coverage when you need it most.
- Pre-Paid Funeral Plan: This is a risky plan you buy from a funeral home. The money is locked in with that one business. A whole life policy is flexible cash your family can use at any funeral home. A cash policy is almost always the safer choice.
Stop Wasting Money. Get the Right Insurance.
Compare prices from trusted life insurers.Get a free quote today and see if you’re overpaying.
Frequently Asked Questions (FAQ)
What's the difference between "whole life" and "final expense"?
“Final expense” is a type of “whole life” policy. “Whole life” is the broad category. “Final expense” just refers to a smaller whole life policy (e.g., $15,000) that is designed to be simple, affordable, and easy for a senior to qualify for.
What's the best company if I have health problems?
A company that offers Guaranteed Acceptance (or “Guaranteed Issue”). Colonial Penn, Gerber Life, and AARP are all excellent, reliable choices. You cannot be turned down.
What's the real cheapest company?
The cheapest company for you depends on your health. If you are healthy, a Simplified Issue policy from a company like Mutual of Omaha or Foresters will be your cheapest, best option.
Why are these companies different from the NerdWallet list?
Because most “best of” lists (like NerdWallet’s) are rating companies for all types of insurance, including massive $500,000 investment plans for 40-year-olds. Our list is only focused on the best companies for senior final expense insurance.
What is a "mutual" company?
A mutual company (like Mutual of Omaha or New York Life) is “owned” by its policyholders. This means you may be eligible to receive a small annual “dividend” payment, which is a nice perk.
This guide is for general education and isn't individual financial, insurance, legal or tax advice. Spot an error? Tell us and we'll review it under our corrections policy.